Homeowners Insurance in Texas
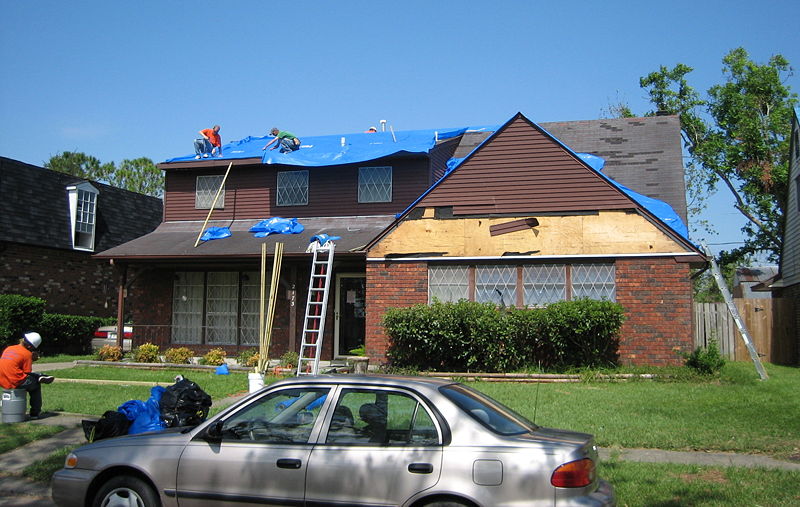
Your home is likely the biggest thing you own, and Texas weather is hard on it. Hail, high winds, and summer storms all hit this state. A homeowners policy helps pay to repair or rebuild your house, replace your belongings, and protect you if someone is hurt on your property.
Quote Texas Insurance is an independent agency. We help Texas homeowners compare coverage, deductibles, and options so the policy matches the home, not just the price. Already a client for business or auto? We can add your home with the same team.
- Real Texas agents
- Help with wind and hail deductibles
- Home and auto bundles
Texas Homeowners: What to Watch For
Texas law does not require homeowners insurance, but your mortgage lender almost always does. Before you buy or renew, check three things most Texas homeowners run into:
- Your wind and hail deductible
- Flood is not included in a standard policy
- Coastal homes may need separate windstorm coverage
Heads up: Flood insurance is a separate policy, and coverage through the National Flood Insurance Program usually has a 30-day waiting period. Don't wait for the forecast.
Before Storm Season, Check:
-
Wind and hail deductible:
Often a percentage of your dwelling coverage, not a flat dollar amount -
Roof settlement:
Replacement cost or actual cash value? It matters after a hail claim -
Coastal windstorm:
Some coastal areas need coverage through the Texas Windstorm Insurance Association (TWIA)
Not sure what your policy says? Send us your declarations page and we will walk through it with you.
What Homeowners Insurance Covers
Most homeowners policies are built from the same main parts. Your exact coverage depends on the policy form and the limits you choose.
Dwelling Coverage
Pays to repair or rebuild the house itself after a covered loss such as fire, wind, or hail.
Other Structures
Covers detached structures on your property, such as a fence, detached garage, or shed.
Personal Property
Pays to repair or replace your belongings after a covered loss at home or sometimes away.
Loss of Use
Helps cover extra living expenses, such as hotel costs, while your home is repaired after a covered loss.
Personal Liability
Protects you if you're legally responsible for someone else's injury or property damage. responsible for someone else's injury or property damage.
Medical Payments to Others
Helps cover guests’ medical bills after an injury on your property, regardless of fault, up to policy limits.
Who Needs Homeowners Insurance in Texas?
- You have a mortgage on your home
- You own your home outright and want to protect it
- You are buying a home and need proof of insurance to close
- You want to bundle your home with your auto policy
Renters can protect their belongings and liability with a renters policy. Read What Does Renters Insurance Cover? to learn more.
A house you rent to tenants usually needs a landlord or dwelling policy instead of a standard homeowners policy. See rental home insurance.
Some carriers offer a discount when you insure your home and car together. Ask us to quote both, and see our auto insurance page.
What Affects Your Homeowners Insurance Rate?
Every carrier prices risk a little differently, which is why comparing matters. Your premium depends on a few main factors.
Location
Your ZIP code, fire station proximity, and local hail and wind risks.
Your Home
Age, size, construction type, and the age and type of your roof.
Coverage & Deductibles
Your dwelling limit, deductibles, and additional coverage.
Claims History
Past claims on the home or by you can affect pricing with many carriers.
As an independent agency, we can compare options from more than one insurance company for your home. Learn more in What Does Home Insurance Typically Cover?
Real Texas Agents Who Explain Your Coverage
Average customer rating
Customer reviews
Real agents on the phone
Online quote form

- Real people, not a phone tree: Call and talk to an agent who knows Texas homes and Texas weather, Monday through Friday.
- Plain-language reviews: We explain deductibles, exclusions, and options before you sign.
- One team for home, auto, and business: Business owners can keep their commercial and personal coverage in one place.
- Local service, Texas focus: Based in Burleson, we serve homeowners across Texas.
Ready to see what the right homeowners coverage looks like for you? Get a free quote today or call us at 844-402-4464 to speak with a real agent.
Homeowners Insurance Coverage Options
In addition to the core coverages above, we can help you look at options that fit your home and your area.
- Dwelling
- Other Structures
- Personal Property
- Loss of Use
- Personal Liability
- Medical Payments to Others
- Flood (separate policy)
- Windstorm (coastal areas)
- Auto Insurance
Own rental property? See our rental home insurance page. Want more reading? Try The Importance of Getting Homeowners Insurance.
844-402-4464